Authors

This article is writen a little diferently to the others I normally publish. It takes on more of a Blog form. For the original article, please go to the LSEG Developer Portal.
I was working on expanding/part 2 of this article on the LSEG Developer Portal, in which I send time-series data to a service that functions, in effect, as a calculator; this service is called ‘Instrument Pricing Analytics’, IPA. Specifically: I used the LSEG Data (LD) Python Library to send index price data and wanted to retrieve back Implied Volatilities.
While doing this, I once retrieved back a data frame filled with <NA>s and I had to troubleshoot it… But where to start?
In this short article, I look into my journey troubleshooting this step, in the hope that it’s of use to you!
Background
I used certain common libraries, such as Pandas, in addition to RD library functions:
You can already see traces of that service I mentioned, IPA, in the 4th line. FYI: Here we are using the LD Library (named the RD Library) version 1.0.0b24.
For more information on the configuration proccess (as per line 9 in the code above), please read this quickstart.
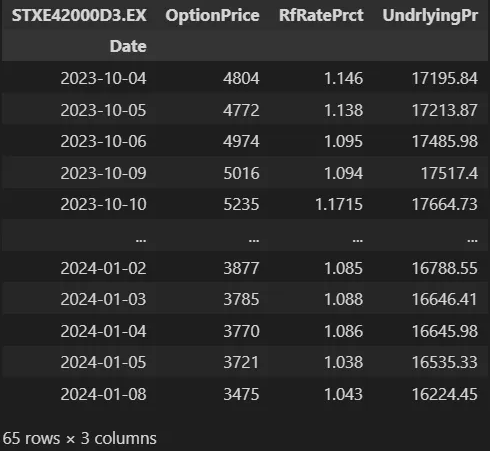
I then gathered data on two Options, a live one (‘2HSI16200L8.HF’) and an expired one (‘HSI19300N3.HF^B23’).
Content Layer
There happen to be three layers to the Data Library. The 1st, called the Access Layer, is the most user-friendly; the 2nd, the Content Layer, is less so, and the Delivery Layer simply sends data requests to LSEG Databases and returns datasets in their ‘rawest’ form — with no/few filters. Below, we will use the Content Layer:
I used VSCode and Intellisense to figure out which arguments were needed in `option.Definition`:
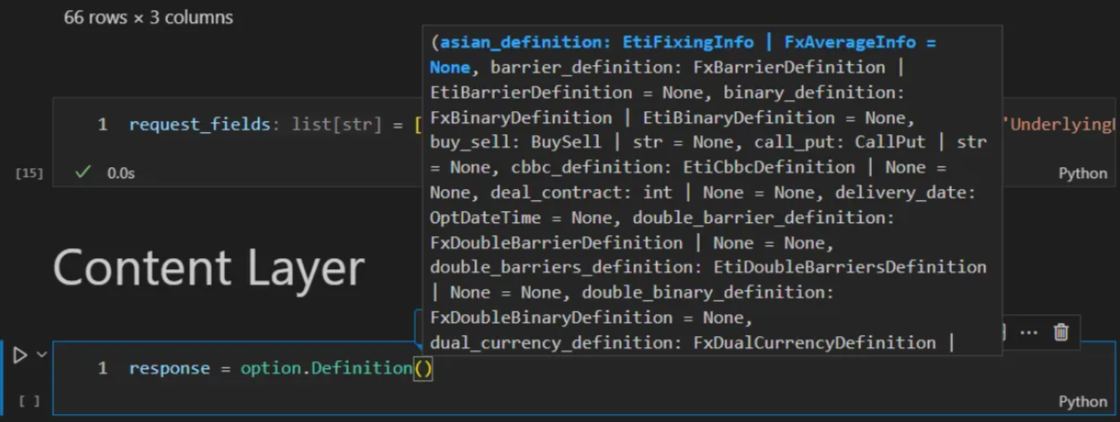
Intellisense is great to quickly write functions like this, however, as we will see soon, it’s not enough.
My code did not work… I kept getting errors:
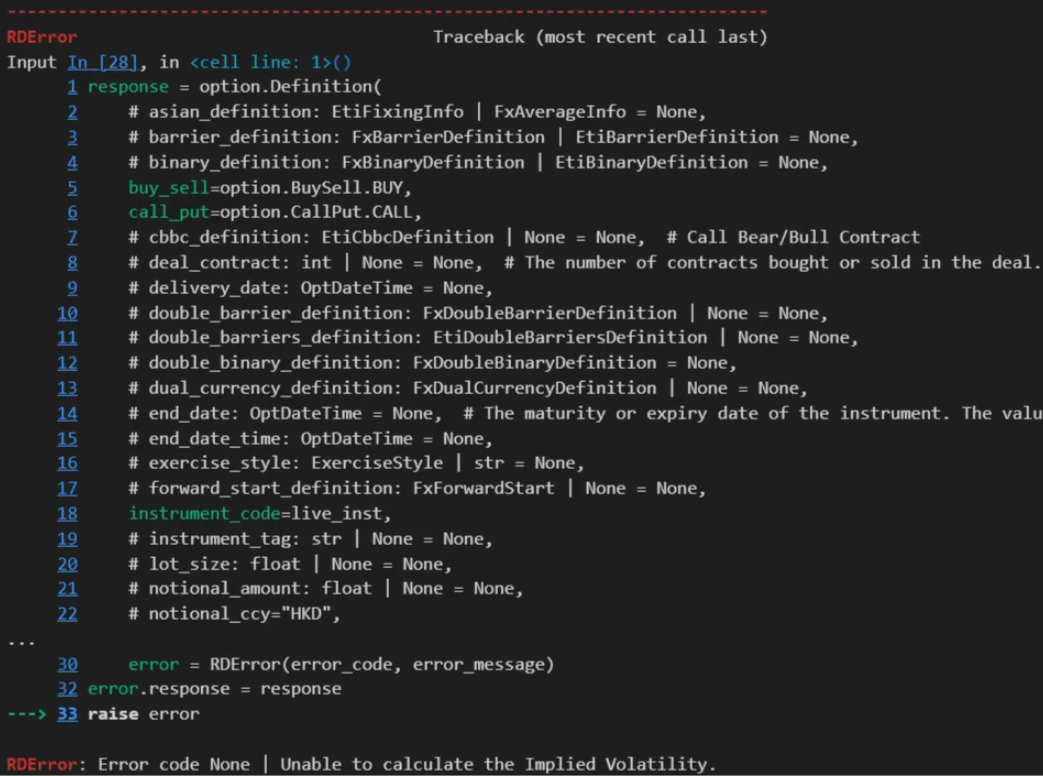
How can I investigate such an issue?
What this Content Layer does is send request to LSEG’s back-end to a specific endpoint. One can see these endpoints on the API Playground:
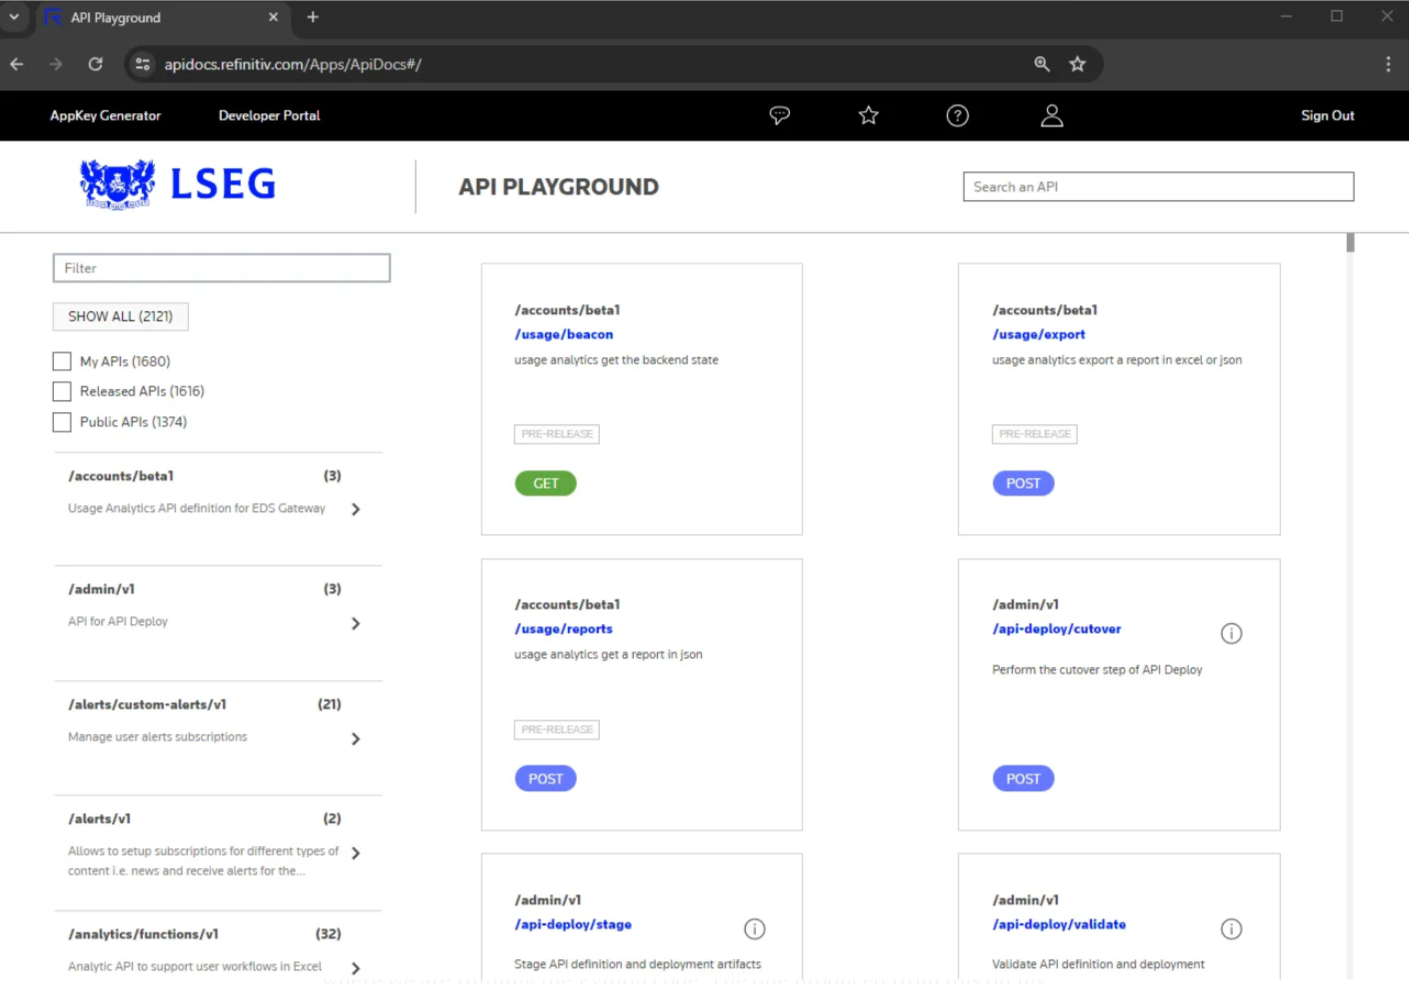
How can you find the endpoint in question that you used? this is where ‘Logs’ come in:
Switching `Logs` On
You can switch on logs with the following code in Python:
You can also switch on logs with the configuration file. If we look into the configuration file used to authenticate ourselves to RD, we can change the “logs”>“transports” >”file”>”enabled” to true, giving us a log file in the path where we are running the Python code. The one produced from this on my machine was called 20240109–1353–11136-refinitiv-data-lib.log. It started with
[2024-01-10T10:59:21.083581+01:00] - [sessions.desktop.workspace.0] - [DEBUG] - [4772 - MainThread] - [_session_provider] - [session_provider] - + Session created: DesktopSession
name = 'workspace'
connection = DesktopConnection
stream_auto_reconnection = True
handshake_url = http://localhos:9000/api/handshake
state = OpenState.Closed
session_id = 0
logger_name = sessions.desktop.workspace.0
You can check which session you are using, out of the Desktop and Platform session, on lign 8. More on these sessions here.
From there, I was looking for the JSON message sent to the IPA service. To find those, I looked for the last instance of api/rdp/data, since we’re looking into our last usage of the RDP API in our code. I looked for the last instance of this and found the request which started with the following:
url = http://localhos:9001/api/rdp/data/quantitative-analytics/v1/financial-contracts
method = POST
headers = {'Content-Type': 'application/json', ... }
json = {'universe': [{'instrumentType': 'Option', 'instrumentDefinition': ... 'ErrorMessage']}
[2024-01-10T10:59:21.083588+01:00] - [RetryTransportBase] - [DEBUG] - [13552 - MainThread] - [_retry_transport] - [_handle_request] - Sending request to http://localhos:9001/api/rdp/data/quantitative-analytics/v1/financial-contracts
[2024-01-10T10:59:23.670464+01:00] - [sessions.desktop.workspace.0] - [DEBUG] - [13552 - MainThread] - [http_service] - [request] - HTTP Response id 9
status_code = 200
text = {"headers":[{"type":"Float","name":"Strike"}, ... , {"type":"String","name":"ErrorMessage"}],"data":[[4200.0,4804.0,1.146,17195.84,"BlackScholes", ... ,"NaN","NaN","NaN",,"NaN","Unable to calculate the Implied Volatility."]]}
It is too long to show in full, but in line 1 & 5, you can clearly see the endpoint that was pinged. Here it’s `quantitative-analytics/v1/financial-contracts`.
API Playground
Coming back to the API Playground, we can now find all the documentation we’re after:
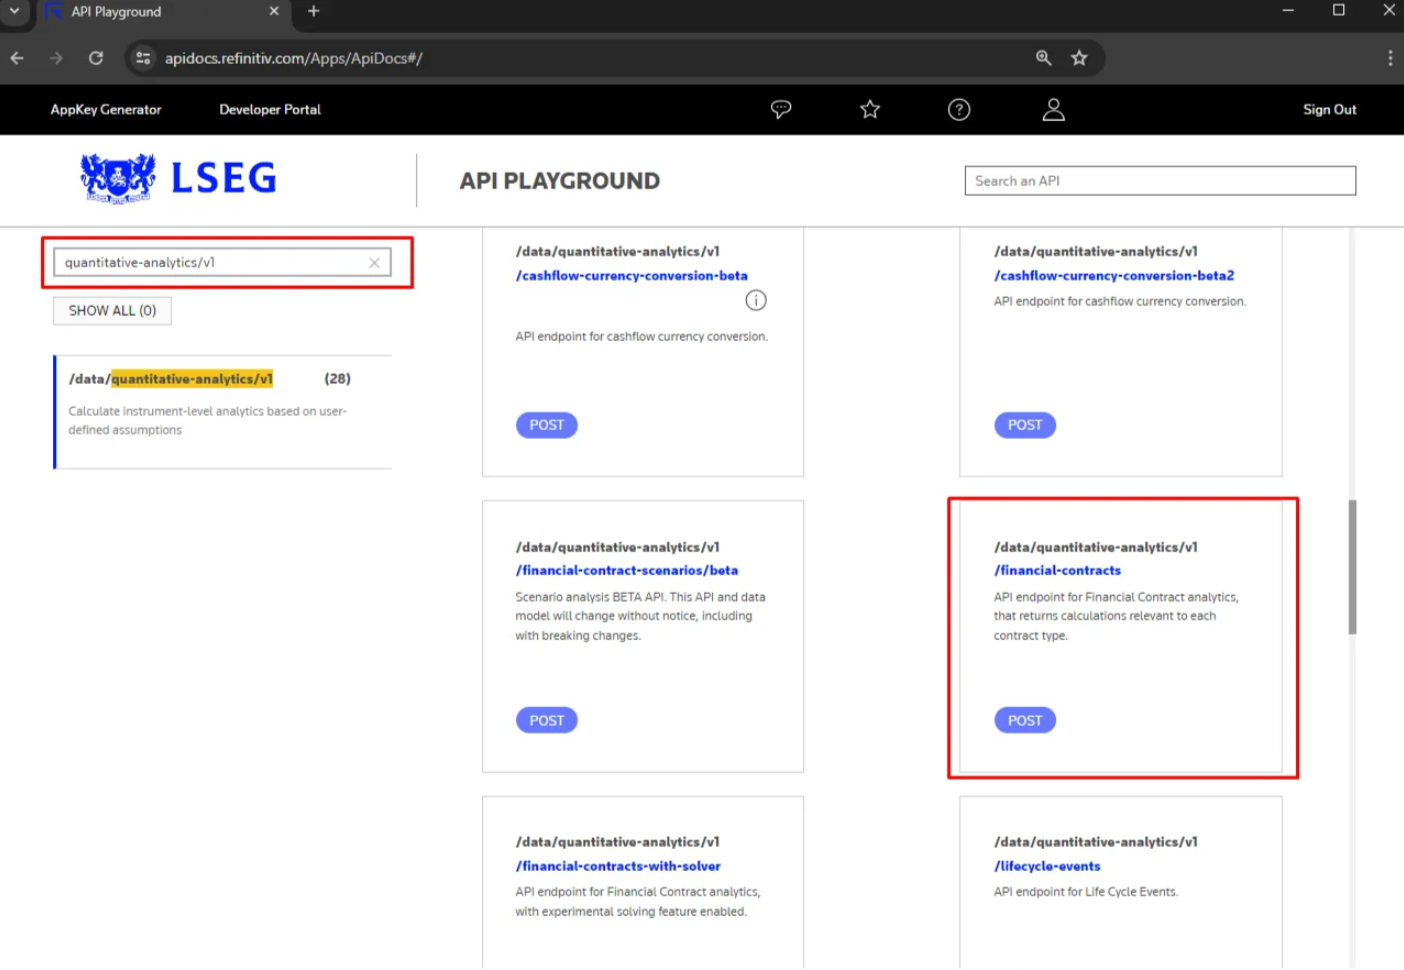
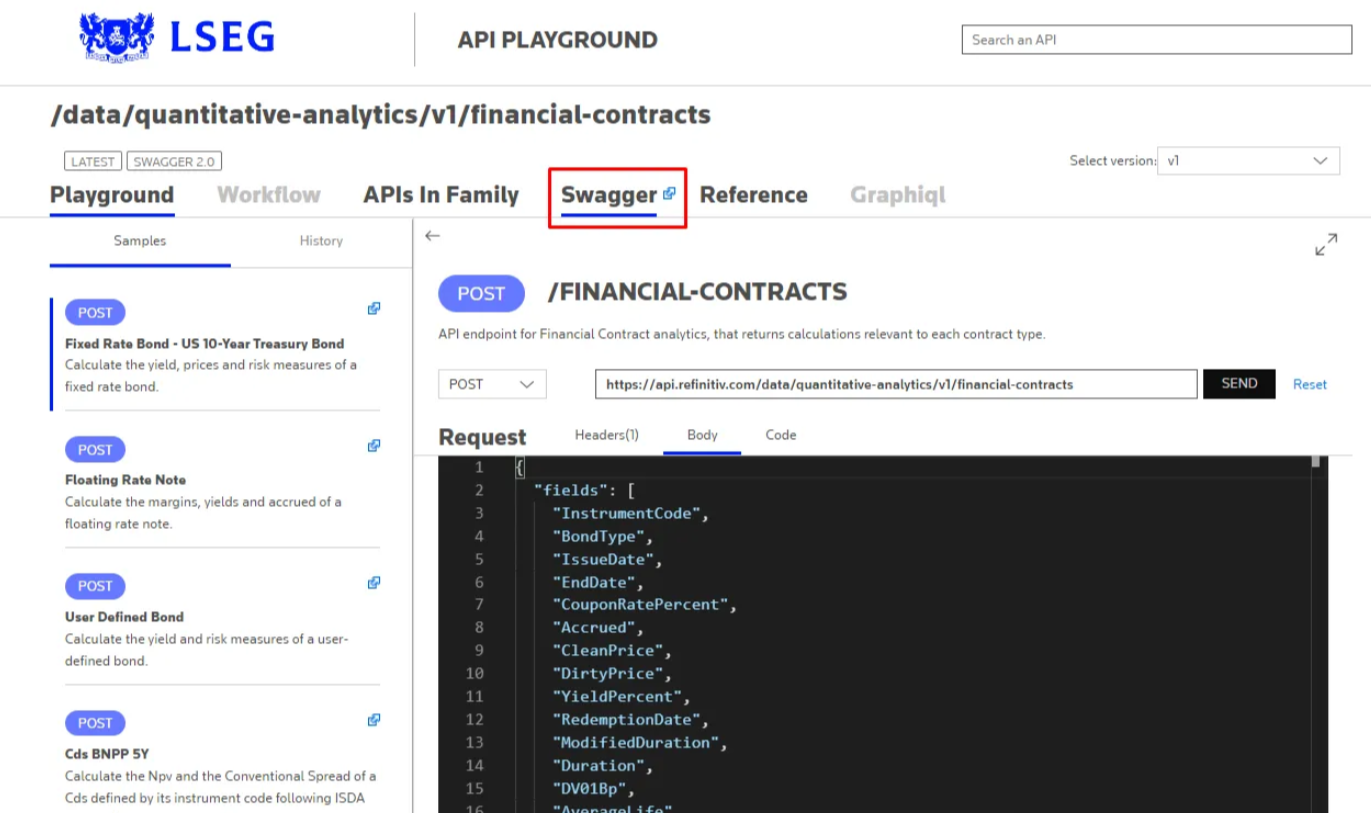
Lookinginto the examples given in the ‘Playground’ tab, I managed to construst a ‘body’ that gave some data similar to what I was after by ommiting data that I originally thought was useful. I could see the data returned by pressing on ‘SEND’:
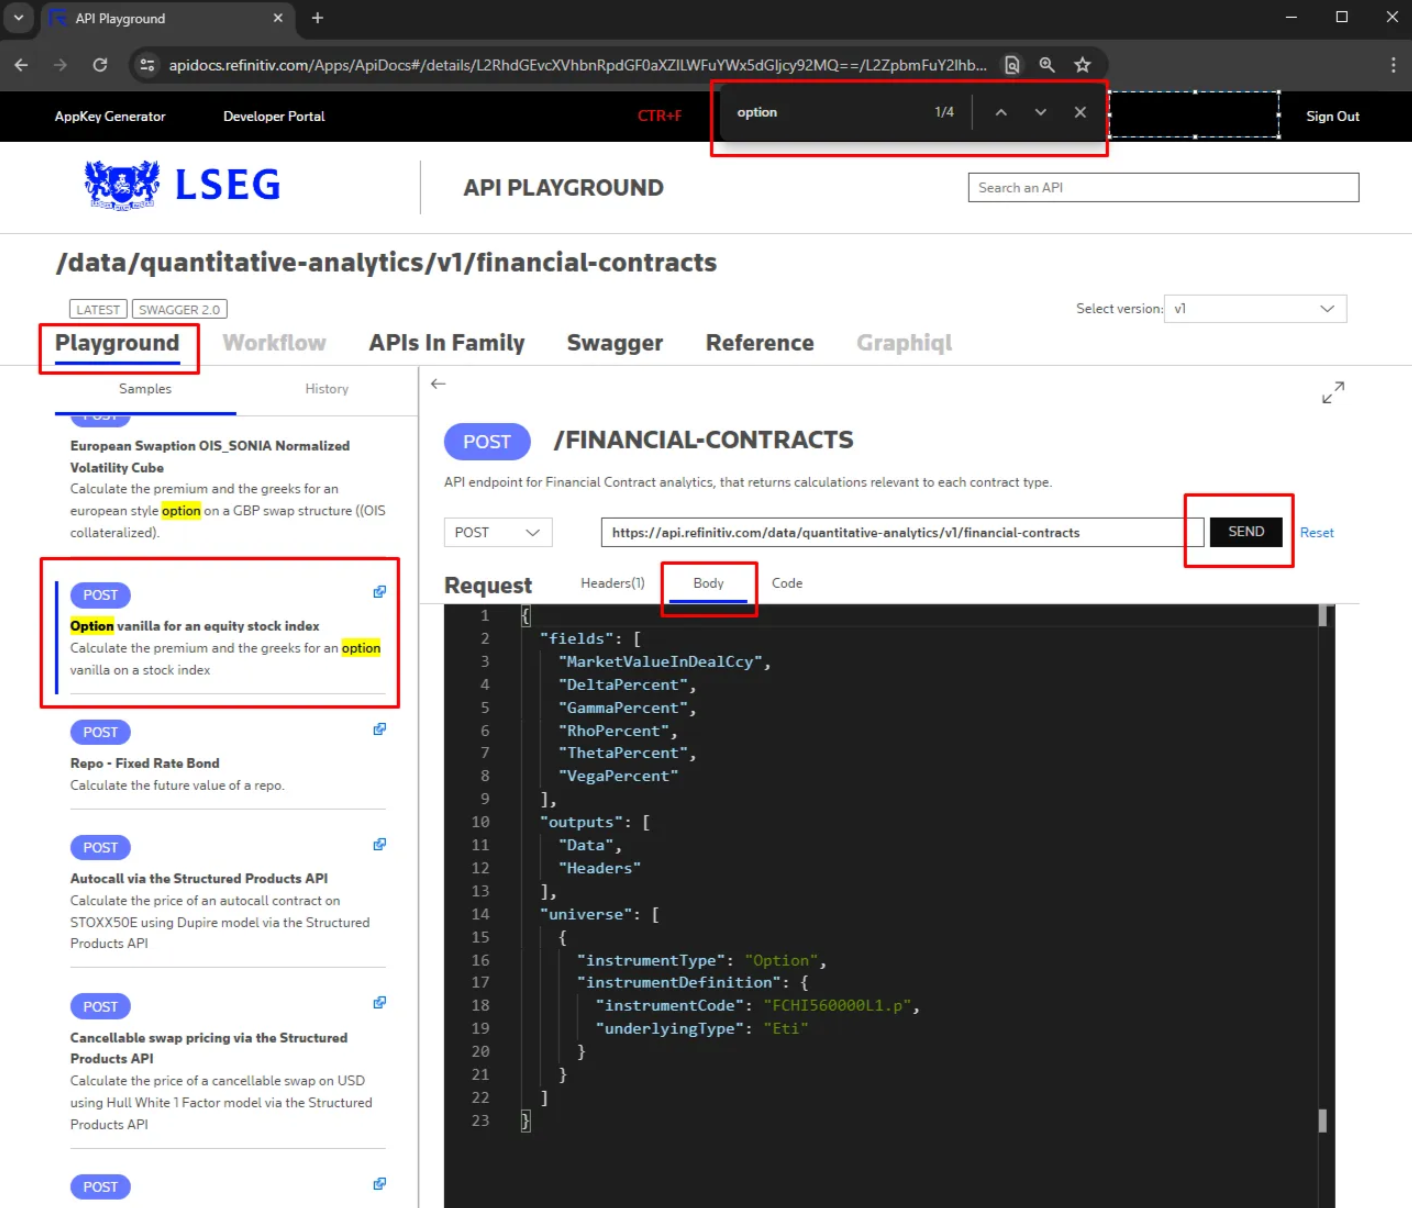
The body that seem to give me some data was:
{
"instrumentType": "Option",
"instrumentDefinition": {
"buySell": "Buy",
"underlyingType": "Eti",
"instrumentCode": 'STXE42000D3.EX',
},
"pricingParameters": {
"marketValueInDealCcy": 4804,
"riskFreeRatePercent": 1.1460,
"underlyingPrice": 17195.84,
"pricingModelType": "BlackScholes",
"dividendType": "ImpliedYield",
"volatilityType": "Implied",
"underlyingTimeStamp": "Default",
"reportCcy": "HKD"
}
}
But what do we do now? Well, there are two options, you could go back to the Content Layer and change the relevent arguments, or use the Delivery Layer. I haven’t shown you how to use that yet, so let’s try it:
Delivery Layer
Batch of 100 requests no. 1/1 started
Batch of 100 requests no. 1/1 ended
| 2HSI16200L8.HF | Strike | MarketValueInDealCcy | RiskFreeRatePercent | UnderlyingPrice | PricingModelType | DividendType | UnderlyingTimeStamp | ReportCcy | VolatilityType | Volatility | DeltaPercent | GammaPercent | RhoPercent | ThetaPercent | VegaPercent | ErrorMessage |
| count | 66 | 66 | 66 | 66 | 66 | 66 | 66 | 66 | 66 | 66 | 66 | 66 | 66 | 66 | 66 | 66 |
| unique | NaN | NaN | NaN | NaN | 1 | 1 | 1 | 1 | 1 | NaN | NaN | NaN | NaN | NaN | NaN | 1 |
| top | NaN | NaN | NaN | NaN | BlackScholes | ImpliedYield | Default | HKD | Calculated | NaN | NaN | NaN | NaN | NaN | NaN | |
| freq | NaN | NaN | NaN | NaN | 66 | 66 | 66 | 66 | 66 | NaN | NaN | NaN | NaN | NaN | NaN | 66 |
| mean | 16200 | 4469.651515 | 1.144962 | 17133.58273 | NaN | NaN | NaN | NaN | NaN | 36.49445 | 0.549396 | 0.000023 | 246.311761 | -0.60418 | 122.613079 | NaN |
| std | 0 | 616.548644 | 0.057065 | 552.082884 | NaN | NaN | NaN | NaN | NaN | 2.622203 | 0.023784 | 0.000003 | 5.615925 | 0.044779 | 1.075281 | NaN |
| min | 16200 | 3441 | 1.02 | 16190.02 | NaN | NaN | NaN | NaN | NaN | 32.32272 | 0.506526 | 0.000019 | 235.036064 | -0.671197 | 120.429082 | NaN |
| 25% | 16200 | 3804.25 | 1.09625 | 16633.4175 | NaN | NaN | NaN | NaN | NaN | 33.48026 | 0.524025 | 0.000021 | 242.250465 | -0.641238 | 121.787159 | NaN |
| 50% | 16200 | 4677.5 | 1.144 | 17183.985 | NaN | NaN | NaN | NaN | NaN | 37.94038 | 0.558198 | 0.000022 | 246.216584 | -0.6303 | 122.641014 | NaN |
| 75% | 16200 | 5004.75 | 1.18775 | 17566.2 | NaN | NaN | NaN | NaN | NaN | 38.56966 | 0.569113 | 0.000027 | 250.933266 | -0.553924 | 123.424069 | NaN |
| max | 16200 | 5568 | 1.2895 | 18238.21 | NaN | NaN | NaN | NaN | NaN | 40.35844 | 0.587471 | 0.000029 | 256.999886 | -0.534717 | 124.543976 | NaN |
| 2HSI16200L8.HF | Strike | MarketValueInDealCcy | RiskFreeRatePercent | UnderlyingPrice | PricingModelType | DividendType | UnderlyingTimeStamp | ReportCcy | VolatilityType | Volatility | DeltaPercent | GammaPercent | RhoPercent | ThetaPercent | VegaPercent | ErrorMessage |
| 0 | 16200 | 4804 | 1.146 | 17195.84 | BlackScholes | ImpliedYield | Default | HKD | Calculated | 39.00143 | 0.562107 | 0.000021 | 241.62978 | -0.65538 | 121.659475 | |
| 1 | 16200 | 4772 | 1.138 | 17213.87 | BlackScholes | ImpliedYield | Default | HKD | Calculated | 38.67129 | 0.561072 | 0.000021 | 242.838419 | -0.647674 | 121.943268 | |
| 2 | 16200 | 4974 | 1.095 | 17485.98 | BlackScholes | ImpliedYield | Default | HKD | Calculated | 39.15167 | 0.567839 | 0.000021 | 246.267948 | -0.646983 | 122.809304 | |
| 3 | 16200 | 5016 | 1.094 | 17517.4 | BlackScholes | ImpliedYield | Default | HKD | Calculated | 39.35019 | 0.569199 | 0.00002 | 246.25132 | -0.650093 | 122.809412 | |
| 4 | 16200 | 5235 | 1.1715 | 17664.73 | BlackScholes | ImpliedYield | Default | HKD | Calculated | 40.29344 | 0.576885 | 0.00002 | 246.282736 | -0.671197 | 122.54165 | |
| ... | ... | ... | ... | ... | ... | ... | ... | ... | ... | ... | ... | ... | ... | ... | ... | ... |
| 61 | 16200 | 3785 | 1.088 | 16646.41 | BlackScholes | ImpliedYield | Default | HKD | Calculated | 33.22061 | 0.523518 | 0.000027 | 244.998808 | -0.54339 | 122.570871 | |
| 62 | 16200 | 3770 | 1.086 | 16645.98 | BlackScholes | ImpliedYield | Default | HKD | Calculated | 33.10405 | 0.522923 | 0.000027 | 245.241265 | -0.540696 | 122.628388 | |
| 63 | 16200 | 3721 | 1.038 | 16535.33 | BlackScholes | ImpliedYield | Default | HKD | Calculated | 33.26945 | 0.519662 | 0.000027 | 242.120688 | -0.542884 | 122.136924 | |
| 64 | 16200 | 3475 | 1.043 | 16224.45 | BlackScholes | ImpliedYield | Default | HKD | Calculated | 32.54961 | 0.507613 | 0.000028 | 236.60269 | -0.534884 | 120.913425 | |
| 65 | 16200 | 3441 | 1.0895 | 16190.02 | BlackScholes | ImpliedYield | Default | HKD | Calculated | 32.32272 | 0.506526 | 0.000029 | 236.548565 | -0.534717 | 120.745756 | |
| 66 rows × 16 columns |
Finding the objects to define your financial contract
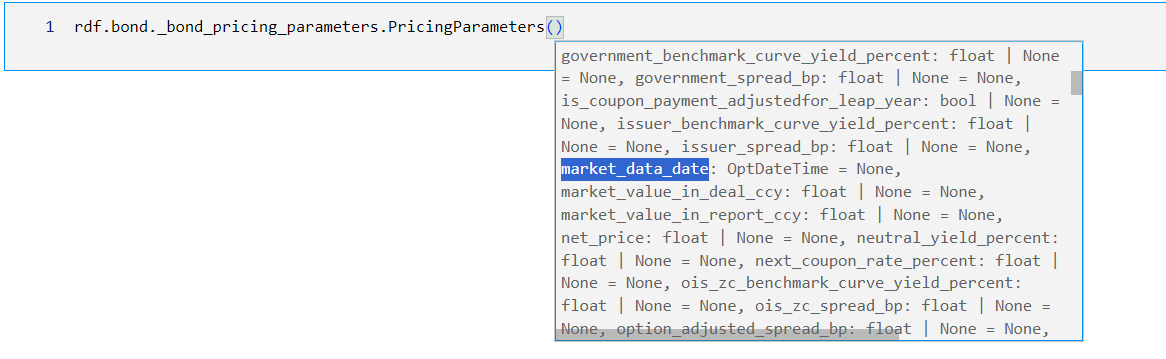
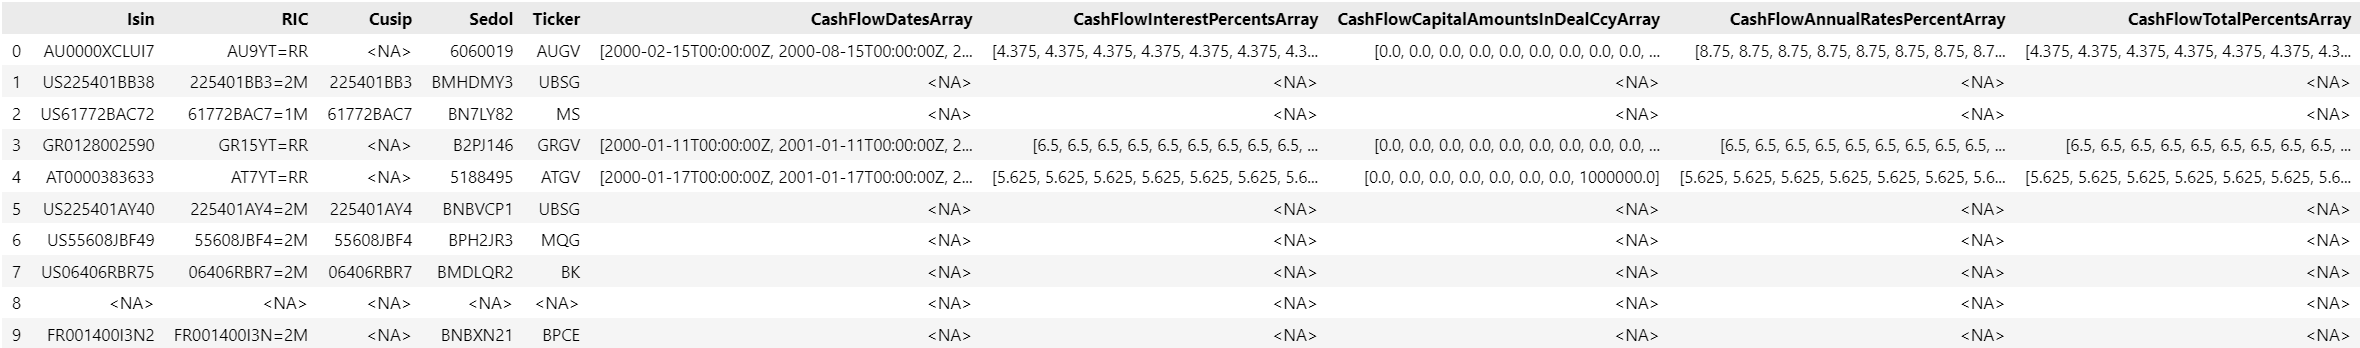
Say you are looking for a way to define a Fixed Income instrument 'as of' a specific date; e.g.: AUSTRALIA, COMMONWEALTH OF (GOVERNMENT) bond AU9YT=RR priced with data from "2000-01-01". You could look into the IPA Documentation, and find `marketDataDate` under "Pricing Parameters"; you could then be tempted to use `pricing_parameters` in "Instrument Definition", but where is that exactly?
I thought it might be in `refinitiv.data.content.ipa.financial_contracts.bond.Definition`, so looked in there:
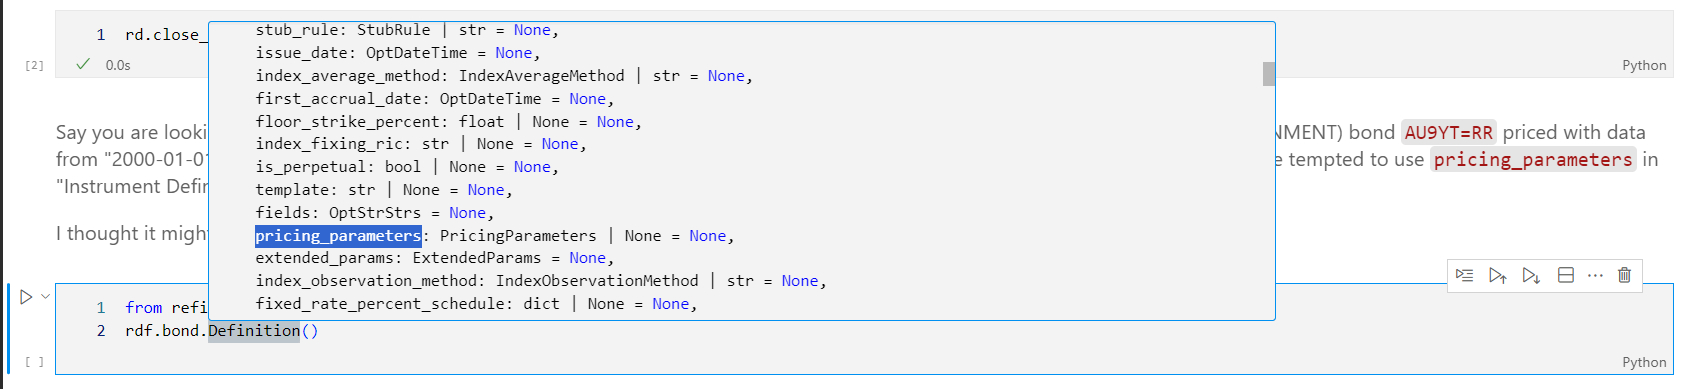
You can see that the `pricing_parameters` variable takes `PricingParameters` objects... but what's that?
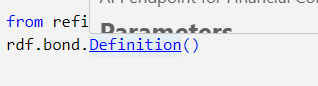
Turns out you can find out more with a Ctrl + click on `Definition` on Visual Studio:
You will then be sent to the source code for `Definition`:
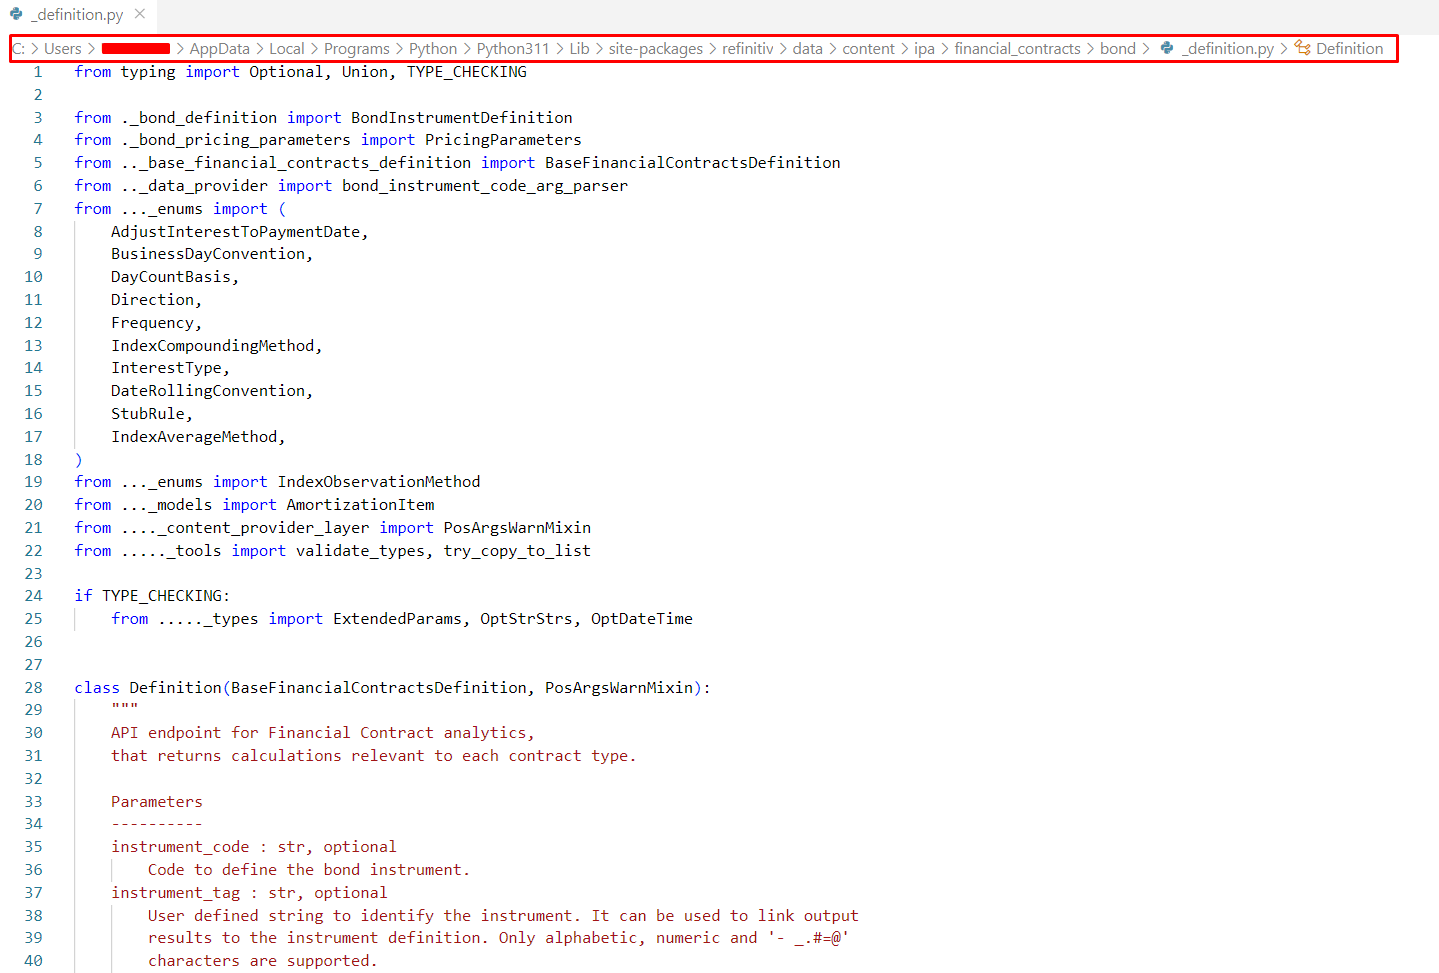
What's interesting here is the path, highlighted in red. You can navigate through the `PricingParameters` (shown in line 4 in the screenshot):
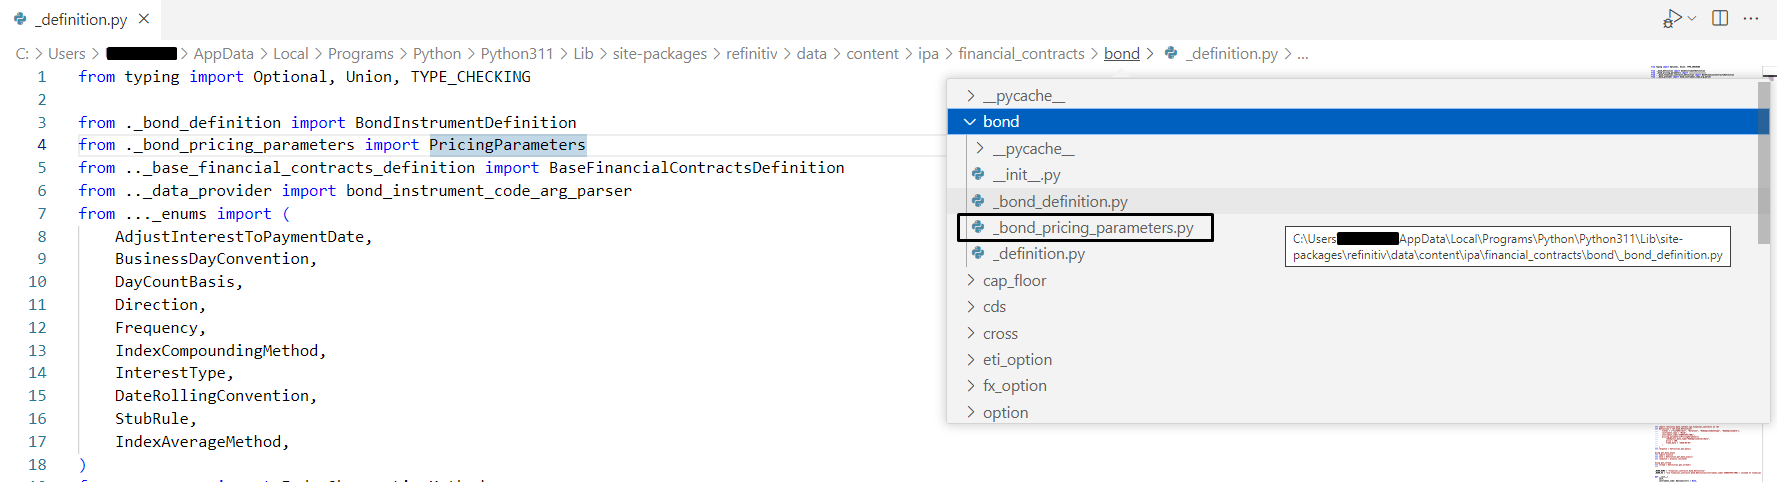
And you can now find the correct module for `PricingParameters`:
P.S.: Trial & Error Troubleshooting
I recently came uppon a second error returned from IPA, ''ErrorMessage" `Unable to calculate the Implied Volatility` and "ErrorCode" `QPS-Pricer.4011`.
I went through the technique above, and found the folowing test call totry out on the API Playground:
{
"universe": [
{
"instrumentType": "Option",
"instrumentDefinition": {
"buySell": "Buy",
"callPut": "Call",
"underlyingType": "Eti",
"instrumentCode": "STXE45500N4.EX",
"strike": 4550
},
"pricingParameters": {
"pricingModelType": "BlackScholes",
"underlyingTimeStamp": "Default",
"volatilityType": "Implied",
"marketValueInDealCcy": 4534.61,
"reportCcy": "EUR",
"riskFreeRatePercent": 3.938,
"underlyingPrice": 4534.61,
"valuationDate": "2023-12-18T11:10:00Z"
}
}
],
"fields": [
"ErrorMessage",
"ErrorCode",
"MarketValueInDealCcy",
"RiskFreeRatePercent",
"UnderlyingPrice",
"Volatility",
"DeltaPercent",
"GammaPercent",
"RhoPercent",
"ThetaPercent",
"VegaPercent"
]
}
What I then did, on the Playground, was remove one (and only one) argument in . I found out, through this trial and error proccess that the the culprit was "marketValueInDealCcy".
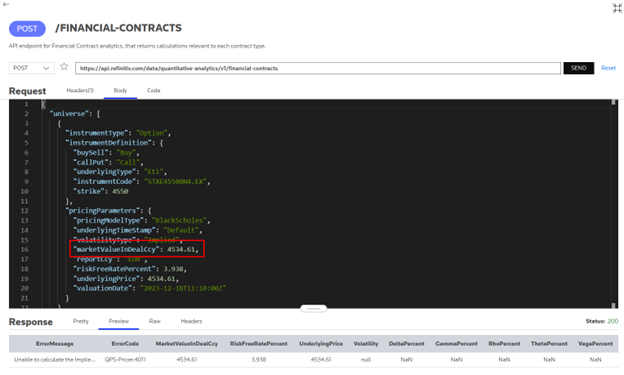
Removing this argument showed that this option was trading at a much lower rate, making Greeks imposible to calculate.
References
Do not hesitate to ask any technical questions you may have about LSEG APIs on the LSEG Developer Comunity Q&A Forum. Please note, however, that this is a Forum aimed at answering technical questions only; for others (e.g.: content-related questions), please reach out to LSEG Support.
For documentation, training articles and videos and more on LSEG APIs, please visit the LSEG Developer Portal.
Related Articles
-
Historical Implied Volatility and Greeks of Index Options 'At The Money' On Update and in the Past using Python Type Hints Part 1
-
Functions to find Option RICs traded on different exchanges
-
Finding Expired Options and Backtesting a Short Iron Condor Strategy
-
Building Search into your Application Workflow
-
Summary of Common LSEG APIs
